Lark’s consumer-facing platform, LARK MONEY, translates the company’s infrastructure proposition into a direct investor use case
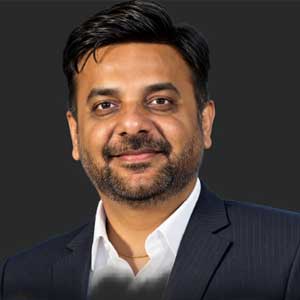
Rohit Pateria, CEO
India’s investment ecosystem has become increasingly digital, making mutual funds, equities and other financial assets easier to own and manage. Yet liquidity against these investments has not always been equally seamless. Investors facing a short-term cash requirement may still resort to redeeming long-term holdings, potentially interrupting their investment strategy. This creates an important opportunity for investment-linked credit: enabling people to access liquidity against eligible financial assets without necessarily selling them.
Founded in 2023, Lark Finserv is addressing this opportunity by building the technology infrastructure that connects wealth with credit. What began with Loan Against Mutual Funds (LAMF) has evolved into an API-first credit infrastructure platform connecting lenders, wealth platforms, fintechs, brokers, mutual fund distributors (MFDs) and investors. At the centre of this strategy is a straightforward proposition: investing and borrowing need not always be competing choices. Lark’s leadership recognised early that India had built significant infrastructure for acquiring and managing investments, while accessing liquidity against those assets remained comparatively fragmented. This insight prompted the company to broaden its ambition from creating a loan product to developing an infrastructure layer capable of supporting multiple participants across the investment-credit ecosystem.
From Lending Product to Embedded Credit Infrastructure
Lark’s transition began with Loan Against Mutual Funds and gradually expanded towards securitiesbacked lending. Along the way, the company developed technology covering the digital credit journey, including customer onboarding, eligibility assessment, KYC, collateral assessment, e-pledging, lender selection, documentation, disbursal and repayment.
The larger shift, however, was strategic. Instead of requiring wealth platforms and fintechs to build lending capabilities independently, Lark began offering APIs, SDKs, white-label journeys and multi-lender orchestration. This allows partners to introduce investment-backed credit within their existing ecosystems while retaining control over their customer relationships.
“That distinction is central to Lark’s positioning. The company does not seek to displace the platform through which an investor already manages wealth. Its infrastructure works behind that relationship, allowing the partner to offer liquidity while Lark coordinates the technological and operational layers required to complete the credit journey. For the end customer, the objective is equally clear: complexity should remain behind the technology rather than becoming part of the borrowing experience”, speaks Rohit Pateria, CEO.
Lark’s consumer-facing platform, LARK MONEY, translates the company’s infrastructure proposition into a direct investor use caseRohit Pateria, CEO
One Stack for Different Digital Maturities
Building infrastructure for financial institutions requires accommodating organisations with very different levels of technological maturity. A large fintech may prefer direct API integrations, while an MFD or smaller wealth firm may need a solution that can be deployed with minimal technology development.
Lark has therefore designed its platform as a flexible stack rather than a fixed product. Partners can choose zero-code journeys, white-label experiences, SDKs or API-based integrations depending on their requirements. They can begin with a specific use case and progressively expand as transaction volumes and digital capabilities grow. “The same philosophy extends to lender orchestration. Different lenders operate with different risk appetites, collateral requirements, product structures and customer profiles. Lark’s infrastructure is designed to route eligible customers across lending options while maintaining controlled workflows”, adds Rohit Pateria.
Trust is consequently built into the architecture through authentication, consent management, data protection, audit trails and process controls. This becomes particularly important when one infrastructure layer must simultaneously address a lender’s focus on risk, a wealth platform’s emphasis on customer retention, a fintech’s demand for integration speed and an investor’s expectation of clarity and convenience.
Making Investment-Backed Liquidity More Accessible
Lark’s consumer-facing platform, LARK MONEY, translates the company’s infrastructure proposition into a direct investor use case. It is designed to enable eligible investors to access capital against investments digitally and, where applicable, within minutes, subject to eligibility, lender approval and regulatory requirements.
LARK MONEY is built on the premise that access to capital should be available when an investor actually needs it, rather than days later. A sudden business requirement, family expense, temporary cash-flow gap, unexpected payment or even a new investment opportunity may arise without warning. In such situations, investors have traditionally had to sell investments, wait for settlement and potentially compromise the benefits of remaining invested. LARK MONEY seeks to provide an alternative by allowing eligible investors to unlock liquidity against their investment portfolios without necessarily liquidating those assets.
The platform is designed to make this process simple and digital, reducing the dependence on lengthy loan applications, multiple interactions and extensive paperwork. Where eligibility, lender approval and applicable requirements are met, the objective is to make investment-backed capital accessible within minutes. By enabling investors to access liquidity while continuing with their longerterm investment strategy, LARK MONEY extends the utility of an investment portfolio beyond wealth creation alone.
“We believe investors should not only be able to grow their wealth, but also use that wealth intelligently when liquidity is needed. LARK MONEY is built around giving investors that flexibility without making the sale of investments the default response to every short-term financial requirement,” speaks Rohit Pateria.
Building the Next Layer between Wealth and Liquidity
Lark Finserv’s next phase is centred on scale, depth and intelligence. The company plans to expand its investment-backed credit capabilities, strengthen relationships with lenders, brokers, wealth platforms and fintechs, and make its infrastructure increasingly plug-and-play. It is also exploring the role of AI and data in areas such as eligibility assessment, lender matching, portfolio insights and customer engagement, while maintaining appropriate controls around financial data and responsible lending.
The larger ambition is to become an infrastructure layer connecting wealth and liquidity across India’s expanding digital investment ecosystem. As investment ownership grows, the next opportunity is not merely helping people accumulate financial assets, but enabling them to use those assets more intelligently when liquidity is required. For Lark Finserv, that means building an ecosystem where selling an investment remains a choice rather than the only route to cash.