Can Parents Invest in Their Child's Name?
Yes, where the investment product permits it.
There is an important difference between:
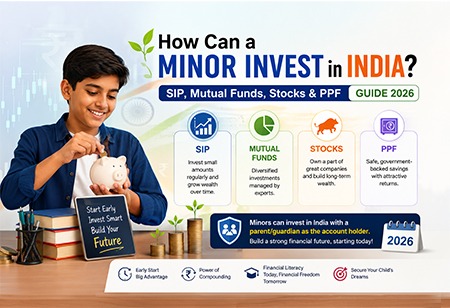
Investing in the minor's name
The minor is the investor/holder and the guardian operates the account.
Investing in the parent's name for the child
The parent remains the legal investor.
These structures can have different consequences for ownership, taxation, succession and control.
If the objective is genuinely to create an investment corpus for the child, families should understand the ownership structure before investing.
Common Mistakes Parents Should Avoid
1. Starting too late
Waiting for the "perfect" investment amount can waste valuable time.
Starting early with an affordable contribution can be more practical than waiting several years to invest a larger amount.
2. Chasing high returns
A teenager's investment portfolio should not become a laboratory for speculative trading.
The goal is long-term financial development, not short-term market excitement.
3. Treating 12% as a guaranteed return
It is not.
The SIP illustrations in this article use 12% purely as a mathematical assumption.
Actual returns can be substantially different.
4. Choosing equity for a short-term goal
If the money is needed soon, market volatility can become a major problem.
The investment should match the time horizon.
5. Investing secretly
A parent may legally manage the account, but hiding the investment from the teenager removes an important opportunity to build financial literacy.
6. Ignoring taxation
Minor investments can create tax consequences through the clubbing provisions.
7. Ignoring the 18th birthday
The Minor-to-Major transition should be planned before the child reaches adulthood.
8. Choosing a platform without checking current rules
Broker and AMC policies change.
Age limits, product availability, documentation and transaction permissions should be checked directly with the institution.
9. Investing in the parent's name without understanding the consequences
Ownership and tax treatment can differ significantly from an investment held in the child's name.
10. Over-diversifying a small portfolio
A teenager does not necessarily need five or ten different funds.
A small number of well-understood investments may be easier to monitor and explain.