Answering FAQs About Investing Before 18 in India
Can a 16-year-old invest in India?
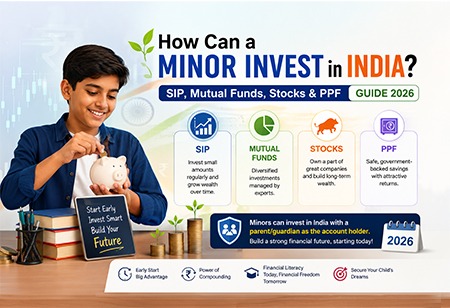
Yes. A 16-year-old can hold permitted investments through a parent or legal guardian, but cannot generally operate the account independently. The exact rules depend on the investment product.
Can a 17-year-old invest in mutual funds?
Yes. A mutual fund investment can be made in the minor's name through a guardian, subject to the AMC's procedures and SEBI's applicable framework.
Can a minor start an SIP?
Yes, a SIP can be established in a minor's mutual fund folio where the selected scheme and platform support it. The guardian manages the account.
Can a minor buy stocks in India?
A minor can hold securities through an eligible guardian-operated demat structure, but cannot independently trade like an adult. Broker-specific restrictions apply.
Can a minor have a demat account?
Yes, a minor demat account can be opened through a parent or legal guardian, subject to broker and regulatory requirements.
Can a minor have a PPF account?
Yes, a PPF account can be maintained for a minor under the applicable PPF rules.
What is the PPF interest rate in 2026?
For July–September 2026, the PPF interest rate is 7.1% per annum. The government reviews small-savings rates periodically.
What is the Sukanya Samriddhi interest rate in 2026?
For July–September 2026, the SSY interest rate is 8.2% per annum. It applies subject to the scheme's eligibility and rules.
Does a minor's investment become tax-free?
No. Minor investments can generate taxable income, and the applicable clubbing provisions may cause the income to be included in the parent's taxable income. Section 10(32) provides an exemption of up to ₹1,500 per minor child, subject to applicable conditions.
Can parents pay a minor's SIP from their own bank account?
For mutual fund investments in a minor's name, SEBI's framework permits payment from the minor's bank account, parent/legal guardian's bank account or certain joint accounts, subject to the applicable requirements. Redemption proceeds are required to go to the verified bank account of the minor.
What happens when a minor turns 18?
The investor becomes a major and must complete the applicable minor-to-major conversion/KYC and bank-detail requirements before independently operating the investment. The guardian's authority does not continue simply because they previously managed the account.
Can a parent invest in a child's name?
Yes, where permitted by the product. The minor is the holder/investor while the parent or legal guardian operates the account.
Is ₹500 enough to start investing?
₹500 can be enough to begin a supported SIP or savings habit, but the minimum depends on the selected product and platform. The amount should be sustainable rather than financially stressful.
Is investing before 18 better than investing after 18?
Starting early can provide more time for contributions and potential compounding, but there is no guaranteed return. The benefit comes primarily from the longer investment horizon and financial habits developed early.