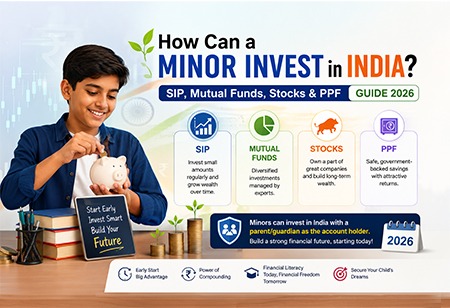
Which Investment Is Better for a Minor?
There is no universal "best investment for a minor."
The right question is:
What is the goal, when will the money be needed, and how much risk can the family accept?
For example:
Goal: Money needed in 1–2 years
Market-linked equity investments may be inappropriate because the value could fall when the money is required.
Goal: Education in 8–10 years
The family may have more scope to consider a combination of long-term market-linked and stable savings products, depending on risk tolerance.
Goal: Very long-term wealth creation
A diversified equity-oriented approach may be considered by families comfortable with market volatility and long holding periods.
Goal: Government-backed long-term savings
PPF or SSY may be relevant where the eligibility and liquidity characteristics fit the goal.
The investment should therefore follow the goal, rather than the other way around.
Investing Before 18: A Simple Age-Based Framework
Teenagers at different ages require different approaches.
Age 8–10: Build the Financial Foundation
The emphasis should be on:
-
saving pocket money
-
understanding needs versus wants
-
learning what interest means
-
introducing compounding
-
explaining what an investment actually owns
The parent can manage the account while involving the child in age-appropriate discussions.
Age 11–13: Introduce Investment Concepts
At this stage, parents can explain:
-
SIPs
-
mutual funds
-
shares
-
diversification
-
risk
-
inflation
-
long-term goals
The child does not need to make investment decisions independently.
Age 14–15: Start Learning Through Real Investments
This can be an appropriate stage to show the teenager:
-
how a SIP works
-
how NAV changes
-
why markets rise and fall
-
how an investment statement looks
-
how returns differ from contributions
The objective should be education rather than chasing returns.
Age 16–17: Prepare for Financial Independence
This is the stage to teach:
-
PAN and KYC
-
bank accounts
-
taxation
-
capital gains
-
nomination
-
demat accounts
-
mutual fund statements
-
investment risk
-
the Minor-to-Major transition
By 18, the teenager should understand not only how much money they have, but why it is invested and how it is managed.