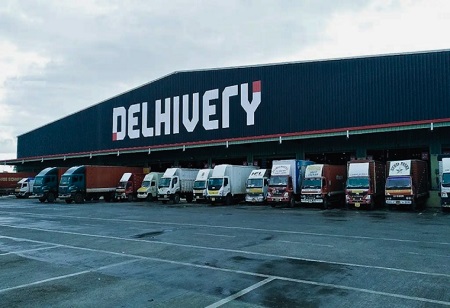
Delhivery shares rallied nearly 10% in early trade on Monday, November 2, after the logistics company returned to profitability in Q2 FY27. The strong quarterly performance and positive brokerage commentary supported investor sentiment. The company reported a net profit of Rs 41 crore, compared with a loss in the year-ago quarter.
Delhivery shares surged 9.67% to an intraday high of Rs 423.35 on the BSE, against the previous close of Rs 386. The stock opened at Rs 400 and was trading 8.83% higher at Rs 420.10 around 10:05 am.
Key Highlights
- Delhivery reported a net profit of Rs 41 crore in Q2 FY27 against a loss of Rs 50 crore last year.
- Operating revenue increased 20% year-on-year (YoY) to Rs 3,066 crore.
- Jefferies retained its Buy rating with a Rs 470 target, while Elara Capital maintained its Buy call with a Rs 620 target.
Delhivery Q2 Results: Revenue Rises 20%, Profit Rebounds
The Gurugram-based logistics company reported a net profit of Rs 41 crore in the September quarter, compared with a net loss of Rs 50 crore in the corresponding quarter last year. It had posted a net profit of Rs 32 crore in Q1 FY27.
Operating revenue increased 20% YoY to Rs 3,066 crore during the quarter, reflecting improved business performance.
Its express parcel business, which handles e-commerce shipments, recorded 32% YoY volume growth and 22% revenue growth. This remains the company's largest business vertical.
The part-truckload (PTL) business also reported volume growth, while improved network utilization and pricing actions supported profitability across business segments.
Also Read: How Today's CFOs Navigate Risk Beyond the Balance Sheet
Jefferies, Elara Capital Maintain Buy Ratings on Delhivery
Global brokerage Jefferies maintained its Buy rating on Delhivery but reduced its target price to Rs 470 from Rs 540. The brokerage cited improving profitability and the potential for a stock recovery following its underperformance against peers.
Jefferies noted that adjusted EBITDA for Q2 FY27 missed its estimates by 23%. However, margins expanded 70 basis points year-on-year. It raised its FY27 earnings per share estimate by 21%, while cutting FY28-FY29 estimates by 8-10%, partly due to expected higher insourcing by Meesho.
The brokerage expects Delhivery's EBITDA to compound at around 52% over FY26-FY28. It identified weak e-commerce growth, increased Meesho insourcing, and rising fuel costs as key risks.
Meanwhile, Elara Capital reiterated its Buy recommendation with a target price of Rs 620. It highlighted strong volume growth, market share gains in express delivery, PTL network expansion, and improved realizations following pricing revisions.
Elara expects pricing actions, automation, and higher network utilization to support further margin expansion. The company is targeting express parcel margins of 16-18% and PTL margins above 15% by FY27-end.
The brokerage also highlighted investments in artificial intelligence, robotics, and new business initiatives as potential long-term growth drivers. However, it cautioned that these initiatives could continue to weigh on near-term profitability.