Mutual Funds and SIPs for Minors
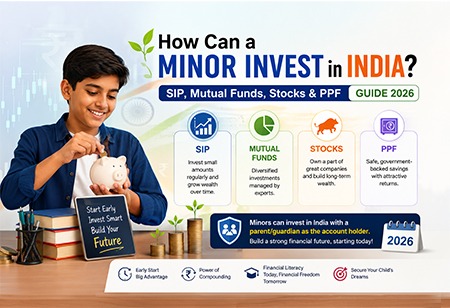
For families seeking a simple way to introduce long-term investing, a mutual fund folio in the minor's name can be one option to consider.
SEBI's framework allows investment in mutual fund units in the name of a minor through a guardian. The minor must be the first and sole holder, while the guardian acts on the minor's behalf.
How does a minor SIP work?
A SIP is simply a method of investing a fixed amount periodically into a mutual fund. For example, a family could decide to invest Rs. 500, Rs. 1,000 or Rs. 2,000 per month in a mutual fund portfolio held in the minor's name, subject to the AMC's current minimum investment and SIP rules.
Given this, the important point is that the SIP amount does not determine whether an investment is suitable. The family should always first consider the purpose and time horizon.
For a long-term goal such as higher education 8–12 years away, market-linked investments may be considered differently from money needed within one or two years.
Discussing portfolio construction, Sauravh Mukherjea from Marcellus Investment Managers has stressed the importance of looking at the portfolio “in totality rather than looking at specific stocks.” For young investors, the lesson is particularly relevant: the objective should be to understand diversification and remain focused on long-term goals rather than reacting to individual market movements.
Why mutual funds can be useful for financial education
A mutual fund can also help parents introduce teenagers to concepts such as:
-
diversification
-
market volatility
-
asset allocation
-
long-term investing
-
expense ratios
-
compounding
-
risk and return
-
taxation
Always remember, the educational benefit can be as important as the financial contribution.
What Is the Minimum SIP for a Minor?
There is no single universal minimum SIP amount applicable to every mutual fund.
Many mutual funds and platforms may offer SIPs at relatively low amounts. However, the minimum can vary by scheme and platform. Therefore, instead of assuming that every minor SIP can be started at exactly Rs 500, parents should check the current minimum SIP amount for the selected scheme.
The more important principle here is “Start with an amount that can be maintained consistently rather than choosing an amount that puts pressure on the family budget."
Illustrative SIP Growth: Investing Before 18
Assumption: SIP starts at age 15, with an assumed 12% annual return. Figures are illustrative and market-linked returns are not guaranteed.
|
Investor Age |
Rs 500/Month SIP |
Rs 1,000/Month SIP |
Rs 2,000/Month SIP |
|---|---|---|---|
|
25 Years |
Rs 2.0 lakh |
Rs 4.0 lakh |
Rs 8.1 lakh |
|
30 Years |
Rs 4.9 lakh |
Rs 9.8 lakh |
Rs 19.6 lakh |
|
35 Years |
Rs 10.8 lakh |
Rs 21.7 lakh |
Rs 43.3 lakh |
|
40 Years |
Rs 23.1 lakh |
Rs 46.2 lakh |
Rs 92.4 lakh |
|
45 Years |
Rs 46.8 lakh |
Rs 93.5 lakh |
Rs 1.87 crore |
|
50 Years |
Rs 91.6 lakh |
Rs 1.83 crore |
Rs 3.66 crore |
Key takeaway: Starting early allows even a relatively small monthly SIP to potentially grow substantially over a longer investment horizon, highlighting the role of consistency and compounding.
How Much Can Rs 500, Rs 1,000 or Rs 2,000 a Month Become?
If we have to answer this, this is where the mathematics of long-term investing becomes useful.
Let’s consider a hypothetical teenager who starts investing at age 14 and continues until age 28.
The following illustration assumes a hypothetical 12% annualised return with monthly compounding and contributions made at the end of each month.
Note: It is not a forecast.
What does this demonstrate?
A Rs 2,000 monthly SIP over 14 years involves total contributions of Rs 3.36 lakh. Under the hypothetical 12% assumption, the illustration grows to approximately Rs 8.64 lakh.
The difference is the effect of investment returns and compounding.
But this is not guaranteed wealth creation. Equity mutual funds can experience substantial fluctuations, and actual returns may be considerably higher or lower than 12%.
What about a single Rs 500 investment?
A single Rs 500 contribution invested for 14 years at a hypothetical 12% annualised return would grow to roughly Rs. 2,500–Rs. 2,700 depending on the compounding convention used.
That is very different from investing Rs. 500 every month.
This distinction is important: Rs 500 once is a small investment. But Rs 500 every month for a certain stipulated year is where we can see an actual difference.
Why Starting Early Matters More Than Starting Big
Teen investing is not primarily about finding the perfect stock or the highest-return fund. But rather, it is about giving money more time to work.
Let’s create a scenario. Consider two teenagers:
Teenager A: Starts investing Rs. 1,000 per month at 14.
Teenager B: Waits until 18 to start investing Rs. 1,000 per month.
Teenager A has already accumulated four years of contributions and investment experience by the time Teenager B starts.
The advantage of starting early therefore comes from two sources:
1. More time for contributions
More months mean more invested capital.
2. More time for returns to compound
Returns that remain invested can themselves generate further returns.
Neither mechanism guarantees a particular final corpus, but both explain why time can be a powerful variable in long-term investing.