Frequently Asked Questions
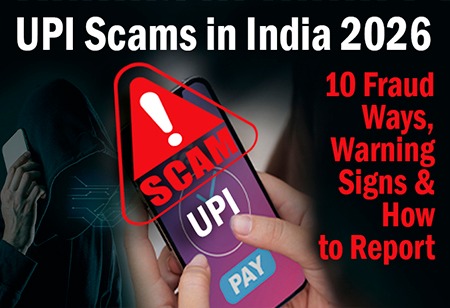
What are the most common UPI scams in India in 2026? The most common are fake collect requests, QR code deception, fake payment screenshots (targeting sellers), fake customer care impersonation, KYC fraud, remote-access scams, and investment fraud — all of which manipulate users into authorising transactions or sharing credentials.
Do I need a UPI PIN to receive money? No. You never enter your UPI PIN to receive money. A UPI PIN is only required to send money or approve a payment. If anyone tells you to enter your PIN to receive a refund or payment, it is a scam.
Can scanning a QR code steal money? Yes. Scanning a QR code typically initiates a payment from your account to the code owner. Fraudsters send QR codes to sellers and buyers with instructions to "scan to receive" - which results in a payment being made from the victim's account, not into it.
Can UPI fraud happen without OTP? Yes. If you personally approve a collect request, scan a QR code and enter your PIN, or install remote-access software, money can be taken without OTP theft. These are user-authorised transactions achieved through deception.
What is the UPI fraud helpline number? 1930 — India's National Cybercrime Helpline, operated by I4C under the Ministry of Home Affairs. Call immediately after any suspected fraud. You can also file a complaint at cybercrime.gov.in.
How do I report a UPI scam? Call 1930, contact your bank's official helpline, file a complaint at cybercrime.gov.in, report within your UPI app, and file an FIR at the nearest police station for significant losses.
Can I recover money sent to a scammer through UPI? Recovery depends on how quickly you report, whether the fraudster's account is frozen before funds are withdrawn, and whether the transaction was unauthorised or user-authorised. Immediate reporting to 1930 gives the best chance of intervention.
How can I identify a fake UPI payment screenshot? Always verify transactions in your bank account or UPI app directly. A screenshot can be fabricated or edited - no screenshot from a payer, however convincing, is proof that money has reached your account. Check your bank balance independently.
Also Read: PNB Pioneers India's First Real-Time NCRP Integration for Enhanced Cybercrime Resolution
Conclusion
UPI's speed is its greatest strength - and the primary reason frauds in India is so damaging when it occurs. The money moves in seconds, and so does the window for intervention. India's anti-fraud ecosystem - 1930, cybercrime.gov.in, NPCI's AI-powered fraud monitoring, I4C's account-freezing capabilities, and the DoT's Chakshu platform - has matured significantly. But the first line of defence remains the user.
The 10 scams in this guide share one common thread: they all work by hacking your attention for sixty seconds - creating urgency, impersonating authority, or exploiting goodwill - before you can pause and verify. That pause is the most important fraud prevention tool available. Slow down. Verify independently. And if you have already been targeted, call 1930 immediately.
About the Author: Shiwani Pradhan is Assistant Editor at Finance Outlook India, with over five years of experience in financial journalism and content production. She specialises in developing fact-based, research-driven content on India’s investment and financial markets. Her work covers investment products, market trends, regulatory developments, and evolving investment opportunities, with a focus on making complex financial topics accessible to readers.
PUBLISHED DATE: 25-09-2026